Key Points
- Siemens’ order backlog reached a record €143 billion in FY2026, up from €117 billion a year earlier. Excluding Siemens Healthineers, approximately €38 billion of the backlog is expected to be recognized as revenue during FY2027.
- Backlog conversion varies considerably between businesses. Siemens expects to recognize €18 billion of Smart Infrastructure’s €25 billion backlog in FY2027, compared with just €12 billion of Mobility’s €65 billion backlog.
- Industrial Business margins reached 16.3%, their highest level since at least FY2016, supported by stronger profitability in Smart Infrastructure and Digital Industries. Group free cash flow also reached a record €12.1 billion.
- Siemens expects 9–11% comparable revenue growth in FY2027, excluding Siemens Healthineers. EPS pre PPA guidance of €10.20–€10.80 implies approximately 13% growth at the midpoint against the comparable FY2026 figure.
Siemens Q4 and FY2026 Financial Performance
Siemens reported 11% year-over-year revenue growth in Q4 FY2026, reaching €23.7 billion, with all four industrial businesses contributing to the increase. Smart Infrastructure provided the largest contribution, supported by strong demand for electrical equipment and data-center solutions.
Profit Industrial Business climbed 22% to €3.9 billion, while the corresponding margin improved by 1.5 percentage points to 16.8%. The stronger operating performance helped Siemens increase earnings per share before purchase price allocation accounting (EPS pre PPA) by 31% to €3.01.
Table 1: Siemens Q4 FY2026 Financial Results
| Indicator | Q4 FY2026 | Q4 FY2025 | Change |
|---|---|---|---|
| Orders | €34.77bn | €21.94bn | +58% |
| Revenue | €23.68bn | €21.43bn | +11% |
| Industrial Business profit | €3.90bn | €3.19bn | +22% |
| Industrial Business margin | 16.8% | 15.3% | +1.5 pp |
| EPS pre PPA | €3.01 | €2.30 | +31% |
| Group free cash flow | €5.56bn | €5.31bn | +5% |
Source: Siemens Q4 FY2026 earnings release. Group free cash flow includes continuing and discontinued operations.
For fiscal 2026 as a whole, Siemens generated revenue of €83.4 billion, up approximately 6% on a reported basis and 8% after adjusting for currency translation and portfolio effects. Industrial Business profit increased 13% to €13.3 billion, with the annual profit margin reaching 16.3%, compared with 15.4% in FY2025. Group free cash flow also reached a record €12.1 billion, up from €10.8 billion a year earlier.
Not all headline figures improved. Net income declined from €10.4 billion to €9.5 billion, largely reflecting the absence of the €2.1 billion gain from the sale of Innomotics recorded in FY2025. EPS pre PPA consequently declined from €12.95 to €11.76, although the latter exceeded Siemens’ most recently raised FY2026 guidance.
Order intake was particularly strong in the final quarter, rising 58% to €34.8 billion, well ahead of revenue growth. The resulting book-to-bill ratio of 1.47 contributed to a substantial increase in Siemens’ order backlog.
Siemens’ €143bn Order Backlog: What Lies Ahead?
Siemens ended fiscal 2026 with a record €143 billion order backlog, up from €117 billion a year earlier. However, the timing of future revenue recognition varies considerably between business segments, with almost half of the backlog concentrated in Mobility’s long-term railway projects.
Table 2: Siemens Order Backlog and Expected FY2027 Revenue Recognition
| Business | Backlog, September 2026 | Expected revenue from backlog in FY2027 |
|---|---|---|
| Mobility | €65bn | €12bn |
| Siemens Healthineers | €41bn | Excluded* |
| Smart Infrastructure | €25bn | €18bn |
| Digital Industries | €11bn | €7bn |
| Other | €1bn | €1bn |
| Total | €143bn | €38bn* |
Source: Siemens Q4 FY2026 investor presentation. Figures are rounded. Expected FY2027 revenue recognition excludes Siemens Healthineers, reflecting its planned deconsolidation.
Smart Infrastructure is expected to recognize approximately 72% of its September 2026 backlog as revenue in fiscal 2027, compared with around 64% for Digital Industries and just 18% for Mobility.
The difference reflects the nature of the underlying businesses. Electrical infrastructure and industrial equipment typically have shorter delivery cycles, while major railway contracts can extend over several years and include long-term maintenance obligations.
Of the backlog excluding Siemens Healthineers, Siemens expects approximately €38 billion to generate revenue in FY2027, followed by €20 billion in FY2028 and €45 billion thereafter.
The distinction is particularly relevant given Siemens’ planned separation from Siemens Healthineers. The healthcare business accounts for €41 billion of the reported backlog but is excluded from the company’s FY2027 financial outlook.
The record order pipeline provides substantial revenue visibility, though not all of it will translate into near-term sales. Its conversion will depend on the pace of project execution, delivery schedules and the mix of business across Siemens’ industrial divisions.
Smart Infrastructure: Electrification and Data Centers Drive Growth
Smart Infrastructure recorded €8.7 billion in orders in Q4 FY2026, up 39% on a comparable basis. Electrification and Electrical Products led the increase, with order growth of 62% and 45%, respectively. The United States was particularly strong, with orders up 70%, supported by large data-center contracts.
Revenue increased 15% on a comparable basis to €7.2 billion as Siemens expanded production capacity and accelerated deliveries. The division’s profit margin improved by 1.6 percentage points to 20.3%, benefiting from higher volumes and operational efficiencies. However, around 0.5 percentage points of the margin came from US tariff refunds.
Data centers have become Smart Infrastructure’s second-largest end market, accounting for approximately 20% of revenue. Siemens ended FY2026 with more than €7 billion in data-center backlog. During the November 12 earnings call, CFO Veronika Bienert said the company expects around 70% of that backlog to convert into revenue in FY2027, with the remaining 30% following in FY2028 (earnings call transcript).
The growing importance of data-center infrastructure is also reflected in Siemens’ commercial relationships. FY2026 buyer-side trade flows records for Siemens available on TenderAlpha Pro identify German transformer technology specialist Maschinenfabrik Reinhausen as an external Siemens supplier, with shipments involving high-voltage electrical switching equipment and transformer components.
In August 2026, Siemens announced a partnership with Reinhausen to develop solid-state transformers for AI-ready data centers. The companies aim to enable more efficient power distribution through an 800-volt direct-current architecture.
The trade flows records establish commercial activity between the companies before the partnership announcement, although they do not identify shipments specifically associated with the new technology.
Mobility: Record Orders and Long-Term Railway Contracts
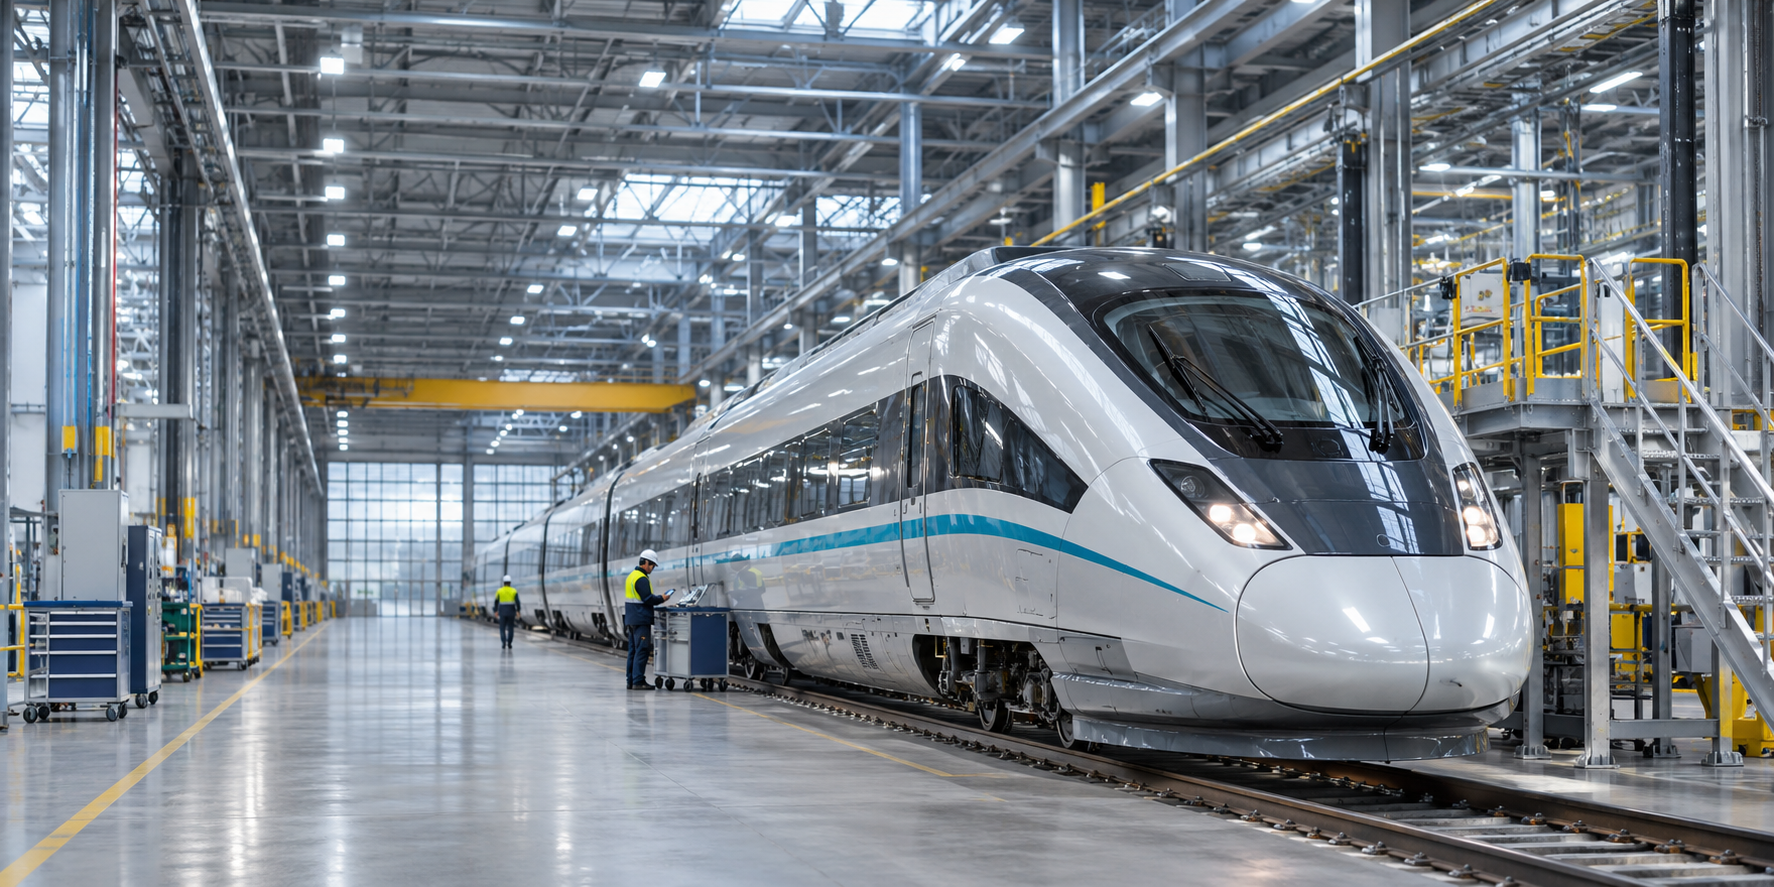
Siemens Mobility recorded its highest-ever quarterly order intake in Q4 FY2026, reaching €10.7 billion compared with €2.5 billion a year earlier. Major contracts included a €2.4 billion high-speed train order in Germany, including maintenance services, and Siemens’ €1.9 billion share of a suburban rail contract involving rolling stock and related services.
Revenue increased 9% to €3.5 billion, supported by higher sales of rolling stock and customer services. The division’s profit margin improved to 9.5% from 8.5%, benefiting from increased revenue and a more favorable business mix.
Full-year performance presents a more nuanced picture. While Mobility’s orders increased 56% to €26.6 billion, revenue grew only 4% to €13 billion, and the annual profit margin slipped from 8.8% to 8.5%.
The gap between order intake and revenue growth reflects the long delivery schedules of major railway projects. Mobility ended FY2026 with approximately €65 billion in backlog, including €22 billion in customer services. Some large projects will contribute revenue over several years, with associated maintenance obligations extending even further.
TenderAlpha’s government contracts data captures one example of this long-term order activity. In October 2025, the Métropole Européenne de Lille awarded Siemens Mobility a €445.7 million contract for 57 automated metro trainsets for Line 2 of the French city’s network. The contract was formally signed in November and also covers spare parts, training and documentation, with the first deliveries expected in late 2028.
The longer-term service business is also visible in Siemens’ B2B relationships. TenderAlpha Pro’s FY2026 supplier-side trade flows records show shipments to Malaysian railway engineering company SMH Rail, including railway components and other industrial equipment.
In February 2025, Siemens Mobility announced a 40-month technical support and spare-parts agreement with SMH Rail covering 58 trains operating on Kuala Lumpur’s metro network. The FY2026 shipping records are consistent with an ongoing commercial relationship, although they cannot establish which individual shipments relate to that agreement.
Digital Industries: Automation Recovery and Software Growth
Digital Industries recorded 15% comparable order growth in Q4 FY2026, reaching €6.4 billion, while revenue increased 10% on a comparable basis to €5.6 billion. Automation orders grew 16%, driven by improving demand in discrete manufacturing, while software orders rose 13%, supported by large contracts in product lifecycle management and electronic design automation.
Software revenue increased 12% on a comparable basis in the quarter to €2.1 billion. For the full fiscal year, software revenue reached €7.2 billion, up 13% on a comparable basis, reflecting Siemens’ growing industrial software business.
The segment’s profit margin climbed to 20.9% from 15.5% a year earlier. However, part of the improvement came from substantially lower severance charges. Excluding these costs, the margin increased from 19.9% to 21.9%, still a significant improvement. Integration expenses related to the Altair and Dotmatics acquisitions also weighed on profitability.
Digital Industries ended FY2026 with an €11 billion order backlog, comprising €7.3 billion in software and €3.8 billion in automation.
Industrial Business Margins at a Decade High
Siemens’ Industrial Business margin reached 16.3% in fiscal 2026, its highest level since at least FY2016. Revenue growth, meanwhile, was more muted than during the post-pandemic recovery, when the company’s topline expanded at double-digit rates in FY2021 and FY2022.
Table 3: Siemens Revenue Growth and Industrial Business Margins, FY2016–FY2026
| Fiscal year | Industrial Business margin | Revenue growth YoY |
|---|---|---|
| 2026 | 16.3% | 6% |
| 2025 | 15.4% | 4% |
| 2024 | 15.5% | 1% |
| 2023 | 15.4% | 8% |
| 2022 | 15.1% | 16% |
| 2021 | 15.0% | 13% |
| 2020 | 14.3% | −2% |
| 2019 | 10.9% | 5% |
| 2018 | 10.4% | 0% |
| 2017 | 11.2% | 4% |
| 2016 | 10.8% | 5% |
Source: Siemens investor materials and annual reports. Revenue growth is nominal, rounded to the nearest whole percentage point. Historical figures reflect Siemens’ reporting perimeter at the time and are not adjusted to a constant portfolio.
The longer-term comparison requires some qualification. Siemens’ portfolio has changed considerably over the past decade, most notably following the Siemens Energy spin-off in 2020. The FY2020 margin also benefited from a €0.8 billion gain related to Siemens’ stake in Bentley Systems. As a result, the improvement from the roughly 11% margins recorded before 2020 cannot be attributed entirely to stronger operating performance.
The more recent trend is clearer. Industrial Business margins remained between 15.0% and 15.5% throughout FY2021–FY2025 before climbing to 16.3% in FY2026. The latest improvement was supported by Smart Infrastructure’s strong performance and recovering profitability in Digital Industries, even as Siemens’ overall revenue growth slowed from the peaks reached earlier in the decade.
FY2027 Outlook and Siemens Healthineers Spin-Off
Siemens expects comparable revenue growth of 9–11% in fiscal 2027, with EPS before purchase price allocation accounting (EPS pre PPA) forecast at €10.20–€10.80 per share. At the midpoint, this represents earnings growth of approximately 13% on a comparable basis, despite the planned deconsolidation of Siemens Healthineers.
The outlook reflects continued growth across Siemens’ three principal industrial businesses, with Smart Infrastructure expected to deliver the strongest revenue increase.
Table 4: Siemens FY2027 Financial Outlook
| Business | Comparable revenue growth | Profit margin |
|---|---|---|
| Digital Industries | 8–12% | 20–22% |
| Smart Infrastructure | 11–13% | 19.5–20.5% |
| Mobility | 6–8% | 8–10% |
Source: Siemens Q4 FY2026 investor presentation. Guidance excludes Siemens Healthineers.
The Healthineers transaction is particularly important when comparing Siemens’ projected earnings with its FY2026 performance.
Siemens plans to distribute 34.1% of Siemens Healthineers’ shares directly to Siemens AG shareholders, at a ratio of one Healthineers share for every two Siemens shares. The transaction, subject to shareholder approval, is expected to take effect in May 2027, leaving Siemens with a minority stake of approximately 33%.
The separation should also strengthen Siemens’ balance sheet through the repayment of approximately €12 billion in Siemens Healthineers debt.
While Siemens reported EPS pre PPA of €11.76 in FY2026, the comparable figure excluding Healthineers was €9.27. Against this adjusted baseline, the FY2027 guidance implies an increase in underlying earnings rather than a decline.
Siemens has also raised its medium-term comparable revenue growth target from 6–9% to 7–11%, alongside expectations for double-digit EPS pre PPA growth.
Achieving these targets will depend on sustained demand for electrification and digital infrastructure, continued recovery in industrial automation, and the execution of Mobility’s expanding order backlog. The planned Healthineers separation will further change Siemens’ financial profile, with its industrial technology businesses accounting for a greater share of reported operations.
Conclusion
Siemens enters FY2027 with record Industrial Business margins and a €143 billion order backlog, providing considerable visibility into future activity. However, the pace of revenue conversion will vary significantly across its businesses.
Smart Infrastructure is positioned to benefit from near-term data-center and electrification demand, while Mobility’s large railway contracts will contribute to revenue over a much longer period. Digital Industries’ recovery in automation and continued software growth will also be important to Siemens’ profitability.
The challenge now is to translate the growing order pipeline into sustained earnings growth while maintaining the margin improvements achieved in FY2026. The planned Siemens Healthineers separation adds another dimension, making comparisons based on Siemens’ continuing industrial operations particularly important.
Explore Siemens’ government contracts and B2B relationships in greater detail through a TenderAlpha Pro demo.
Disclaimer: This article is intended for informational and research purposes only. It does not constitute investment advice or a recommendation to buy or sell any security.